

 Back to Blogs
Homeowners Insurance: What It Covers
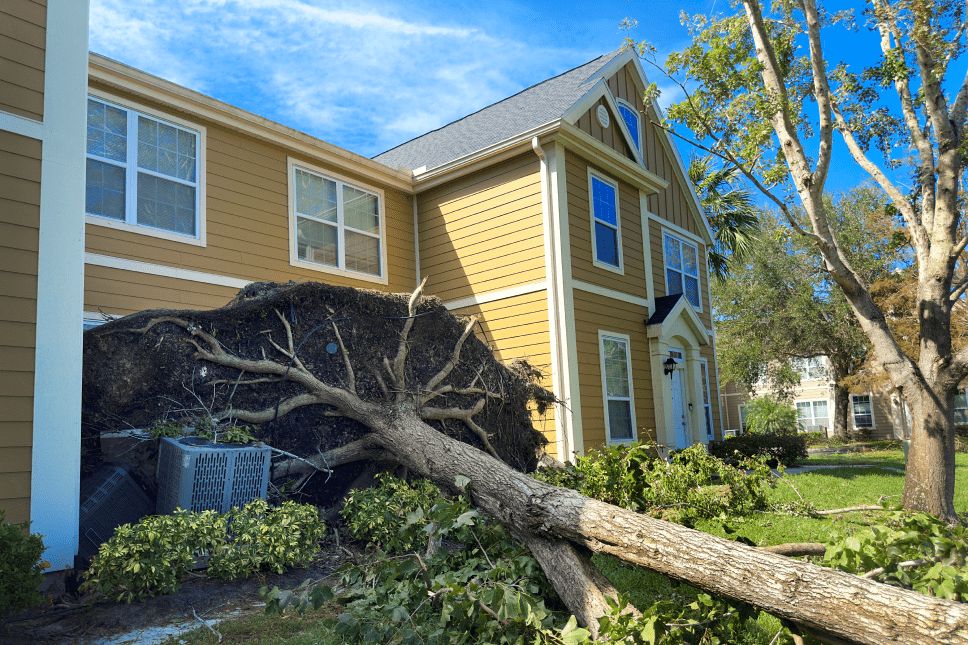
When a major storm sweeps through Asheville, the damage it leaves behind can feel overwhelming. Roofs, windows, siding, and front doors often bear the brunt of wind and debris. For many homeowners, there’s a big question lingering in the aftermath: Will my homeowners insurance help cover the cost to repair or replace these things?
The short answer is often yes – but it also comes with some important caveats. Let’s break it down so you know what to expect when it comes to windows, doors, siding, and the role your homeowners insurance plays after a storm.
How homeowners insurance usually works
Most homeowners insurance policies include something called “dwelling coverage.” This is the part of your policy that helps pay for repairs to the physical structure of your home – your walls, roof, windows, siding, and even your attached garage – if they’re damaged by what the policy calls a “covered peril.”
So, what’s a covered peril? For many policies, it’s things like wind, hail, fire, falling trees, or vandalism. So, if a hurricane blows out your windows or a tree branch comes crashing through your siding, your policy should cover the cost of repairs.
Of course, some things aren’t covered by homeowners insurance, including:
- Normal wear and tear
- Damage from neglect
- Damage from floods or earthquakes, which are covered under separate policies
On top of knowing what’s covered, it’s also worth knowing how your policy pays out.
Some homeowners insurance policies use Actual Cash Value (ACV), which factors in depreciation, so older windows might be valued at much less than the cost to replace them today. Others use Replacement Cost Coverage (RCC), which pays the full cost to replace damaged items with new ones of similar quality. That difference can be huge after a big storm, so it pays to check your policy details ahead of time.
What’s covered under homeowners insurance?
What about the facets of your home you see every day – your windows, doors, siding, even your garage door? Are these covered? The answer: it depends.
Does homeowners insurance cover windows? What about doors?
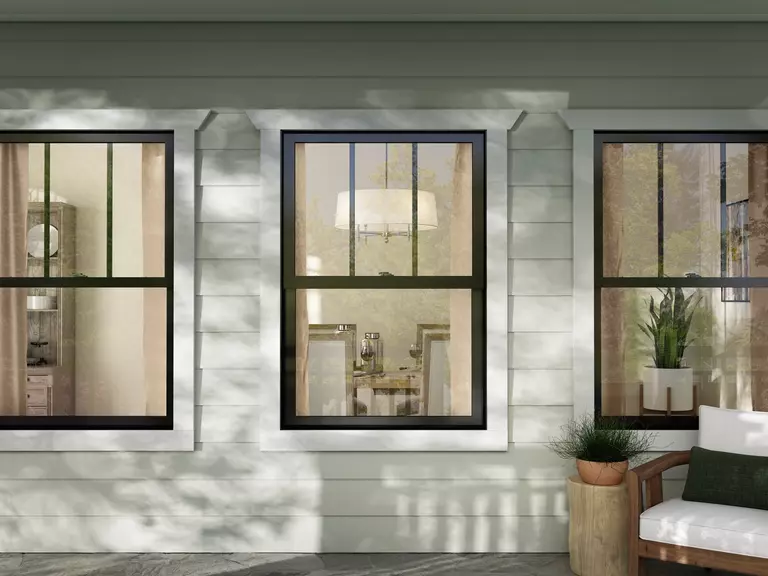
For windows, if they’re damaged by wind, hail, or flying debris, most homeowners insurance coverage will help pay to repair or replace them. The same goes for front doors and garage doors. If a storm damages them, your policy usually helps cover the cost.
Need an example?
- Say that one window on the front of your home breaks, but the rest are fine
- Some policies will pay to replace just the one
- Others may require all the windows on that side to be replaced so everything matches
As you can see, it depends on how your coverage is written, so it’s worth a quick call to your agent if you’re not sure.
Does homeowners insurance cover siding replacement?
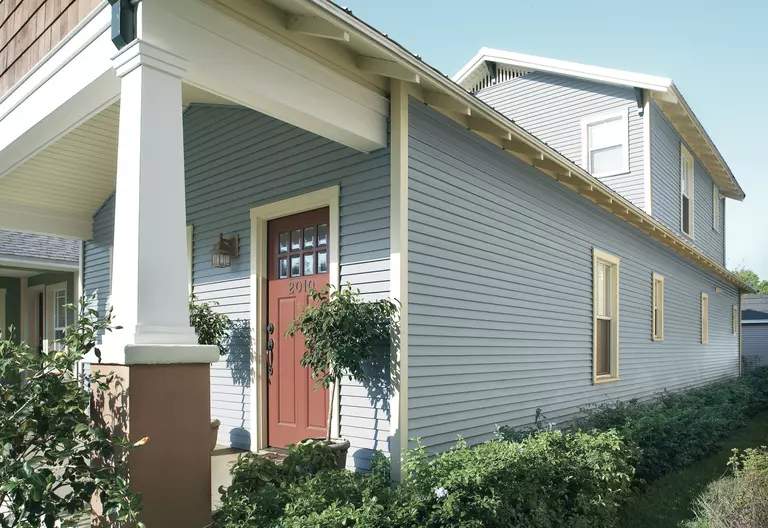
Siding is typically treated the same way. If a tree branch crashes into it or hail leaves dents across one side of your home, your policy might pay to repair or replace the damaged section. Depending on the insurer, your coverage may even cover replacing the entire side for a consistent look.
Does homeowners insurance cover all remodeling?
No; remember that this insurance doesn’t cover everything.
Don’t count on damage from aging materials, ongoing leaks, or routine maintenance issues to be paid for by your insurance company. Insurers draw a hard line between storm damage and things that happen because a home wasn’t properly maintained.
The role of natural disasters
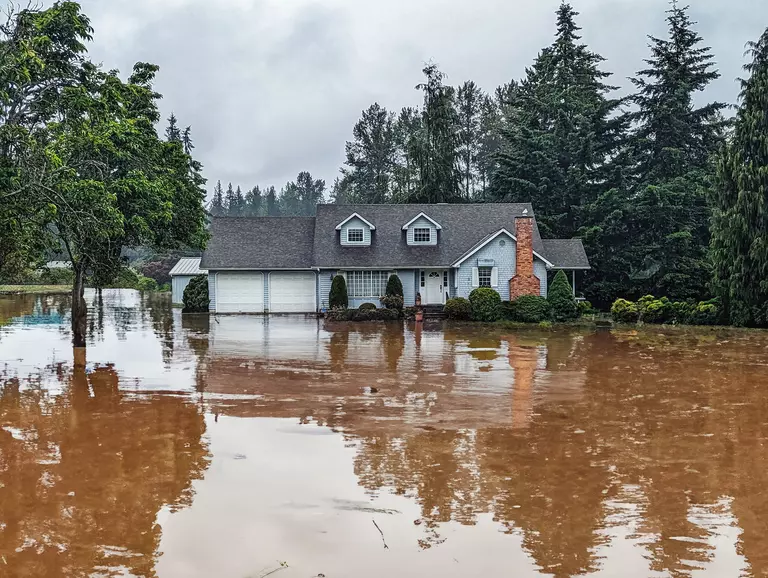
Living in Asheville means dealing with strong storms from time to time. While wind damage is typically covered, water damage from flooding often isn’t unless you have separate flood insurance.
Here’s where it gets tricky: wind damage and flood damage are treated differently by insurance companies.
If wind blows out your windows and rain gets in, the resulting water damage is often covered under your standard homeowners policy. But what if rising floodwaters from the ground damage your home? Unfortunately, that usually requires a separate flood insurance policy. The same storm can cause both types of damage, but how it entered your home matters when it comes to coverage.
Bottom line: Check your homeowners insurance policy carefully to see what’s protected and covered and to learn whether taking out additional coverage is a good idea.
How upgrades can impact your rates
When the time comes to replace damaged windows, you should just swap them out for identical ones, right? Not necessarily.
In fact, replacing storm-damaged windows, doors, or siding with stronger, more storm-resistant materials can help lower your insurance premiums over time. Certain products both protect your home from severe weather and can gain you discounts from insurance companies, provided those products are certified with damage-mitigating features. These are products like:
And don’t forget energy efficiency; modern windows often come with low-E glass and tighter seals that can help lower heating and cooling costs. With enough energy-efficient windows in your home, you could see year-round savings along with better protection.
Coverage limits & deductibles
Even if damage from a storm or some other event is covered, it’s worth reviewing your homeowners insurance policy before making any big decisions. Some policies pay the full replacement cost, while others only pay the depreciated value. And remember, you’ll still have to pay your deductible before coverage kicks in.
Also, in some regions, policies include a special hurricane deductible that applies only when wind or named storms cause the damage. These deductibles are sometimes a percentage of your home’s insured value rather than a flat amount, so they can be higher than you might expect.
That’s why it’s always smart to call your insurance agent and get clear answers on what’s covered, what isn’t, and what your limits look like. A good rule of thumb is to check these facts once a year, before hurricane season rolls around, so you’re not surprised later.
Find new windows at Window World of Asheville
If your home was hit by sudden storm damage, homeowners insurance often helps cover the cost to repair or replace windows, doors, siding, and more. But the details in your policy matter, and it’s always best to review it carefully – or talk to your agent – so there aren’t any surprises.
And if you’re thinking about upgrades, choosing storm-resistant products now can pay off later with better protection and possible savings on your insurance premiums. At Window World of Asheville, we help homeowners recover after storms with durable, energy-efficient windows, doors, and siding that stand up to the elements. If your home needs repairs – or you’re ready for an upgrade – request your free, no-obligation quote today. We’ll help you find the right products for your home and budget.